The views expressed are Ed le Feuvre's personal market observations and do not constitute investment advice, a financial promotion or a recommendation to buy or sell any security. Read the full disclaimer.
Dear Quay Financials
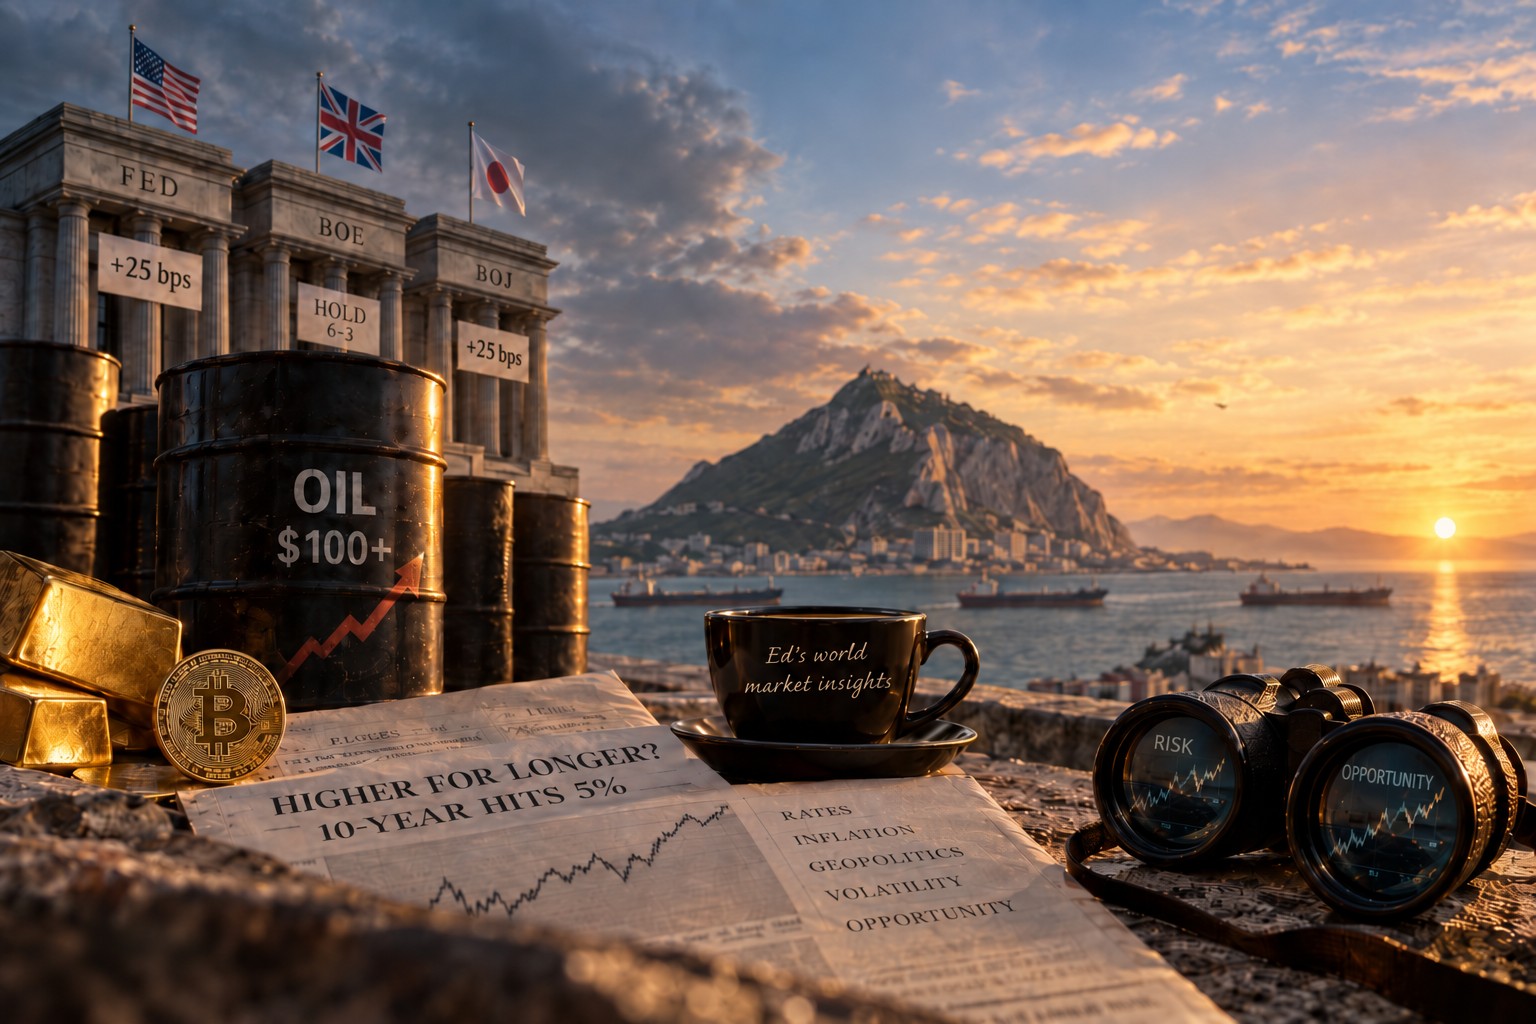
Saturday morning in Gibraltar, coffee in hand, looking out across the Strait, and it is one of those mornings when the view seems determined to make the world look rather more orderly than it has been. The water is calm, Africa sits quietly on the horizon and, for a few minutes at least, a 5% Treasury yield, $100 oil and three rather busy central banks feel comfortably distant. Markets, unfortunately, have never shown much respect for the view.
What was striking was not the tightening itself, but the market's ability to absorb it. The Nasdaq finished the week higher, the S&P 500 was almost unchanged and Bitcoin rallied sharply into Friday. Elsewhere the picture was less forgiving. The Dow lost 1.7%, small caps fell 1.5% and European equities gave back their earlier gains.
Oil supplied the week's other contradiction. Brent traded close to $110 as threats to Saudi infrastructure intensified, then retreated as China pressed Iran to restrain Houthi attacks and Saudi Arabia worked to restore pipeline capacity. The barrel ended the week close to where it began, but the route remained anything but settled.
Let's turn to the week.
Recap: Where We Left Off (Week 37)
Last week left us with Brent above $100, the US 10-year yield near 5% and three central banks confronting different versions of the same inflation problem. The key question was whether policy tightening would become the dominant market force, or whether falling oil and resilient earnings could keep risk assets steady.
What occurred was more tightening than markets had faced for some time. The Federal Reserve raised the federal funds target range by 25 basis points to 3.75% to 4.00%, its first increase since 2023. The Bank of Japan raised its policy rate to 1.25%, the highest in 31 years, while the Bank of England held at 3.75% by a 6-3 vote, with the minority favouring a hike. What surprised was the resilience of technology shares and digital assets despite a 5% Treasury yield. What did not materialise was a sustained oil breakout: after trading near $110, crude ended the week broadly flat.
If you missed last week, you can find it here.
This Week: Two Hikes, One Hold and a 5% Treasury; Markets Absorb the New Cost of Money
Weekly Market Table
| Market | Week-end level | Weekly move | Year to date |
|---|---|---|---|
| S&P 500 | 7,650.50 | -0.1% | +11.8% |
| Nasdaq Composite | 26,522.55 | +0.7% | +14.1% |
| Dow Jones | 51,682.64 | -1.7% | +7.5% |
| Russell 2000 | 2,860.40 | -1.5% | +15.2% |
| STOXX Europe 600 | 635.45 | -0.6% | +7.3% |
| FTSE 100 | 10,659.13 | +0.1% | +7.3% |
| Nikkei 225 | 65,018.95 | +1.6% | +29.2% |
| Gold, New York | $4,424.90 | +1.3% | +2.0% |
| Bitcoin | c. $80,900 | c. +2.7% | c. -8.5% |
| Brent crude | $104.87 | c. +0.2% | c. +71.4% |
| WTI crude | $100.30 | +0.2% | c. +73.4% |
| US 10-year Treasury | 5.00% | +3 bps | +82 bps |
Closing data for the week ended 18 September 2026. Year-to-date moves are measured against 31 December 2025 using the historical baseline preserved from the published Week 37 table. Bitcoin is indicative because digital assets trade continuously. Oil figures remain approximate where contract and closing conventions differ. A rise in bond yield is shown as negative for bond prices. Bitcoin and Treasury vendor convention differences are retained in the workbook audit notes rather than rewriting the prior publication.
US & Global Equities
- United States: The S&P 500 lost only 0.1% and the Nasdaq gained 0.7% despite the Fed hike and a 10-year Treasury yield around 5%. The headline resilience was real, but it was concentrated. The Dow fell 1.7%, its worst week since March, showing that the market was rewarding growth durability rather than offering a broad endorsement of tighter policy.
- Breadth and size: The Russell 2000 fell 1.5%. Smaller companies remain more exposed to refinancing costs, domestic demand and wage pressure. With the risk-free rate around 5%, balance-sheet quality is becoming a more visible part of equity performance.
- Europe: The STOXX 600 fell 0.6% after a 1.1% Friday decline erased earlier gains. Autos and telecoms led the sell-off, while the region also had to absorb tighter global policy and an energy shock that remains materially larger than it was before the Middle East conflict.
- Capital flows: US equity funds recorded a fourth consecutive weekly outflow, with $31.44 billion leaving in the week to 18 September. The index surface remains calmer than the underlying allocation data.
Gold, Digital Assets and Other Assets
- Gold: US gold futures settled at $4,424.90, up about 1.3% from the prior week's published level. The rebound came as oil retreated from its midweek highs, easing the most acute inflation fears. Gold therefore recovered even while the Fed tightened, a reminder that the interaction between real yields, oil and geopolitical risk matters more than any single headline.
- Bitcoin: Bitcoin finished Friday around $80,900. Against the preserved Week 37 published baseline of approximately $78,750, that is a gain of about 2.7%. A later daily-data source uses a different 11 September cut-off and year-end convention. The workbook records both rather than smoothing away the discrepancy.
- Oil: Brent ended at $104.87 and WTI at $100.30. Those closes conceal a much more volatile week in which Brent approached $110 before easing. The market moved from fear of Saudi infrastructure disruption towards cautious relief as China urged Iran to restrain Houthi attacks and Saudi Arabia worked on restoring East-West pipeline capacity.
- Commodities: The broader message remains inflationary rather than uniformly bullish. Energy is still expensive, but Friday's retreat showed that geopolitical risk premia can compress quickly when physical supply routes appear less threatened.
Macro & Policy
- Federal Reserve: The FOMC voted 12-0 to raise the target range by 25 basis points to 3.75% to 4.00%. Its statement said economic activity was expanding at a solid pace, domestic spending remained resilient and inflation remained elevated. This was a tightening decision justified by inflation rather than a response to economic weakness.
- Bank of England: The MPC held Bank Rate at 3.75% by 6-3, with three members voting for 4.00%. August CPI was 3.1%, and the Bank explicitly linked the risk of further inflation to the protracted Middle East conflict and higher energy prices.
- Bank of Japan: The BOJ raised its policy rate from 1.00% to 1.25% by 7-2, the highest level in 31 years. The decision was expected, but it reinforces a broader point: Japan is no longer an automatic source of ever-cheaper global funding.
- Bond market: The US 10-year Treasury finished around 5%. That level now sits alongside a higher policy rate rather than anticipating one. The distinction matters because the cost of capital has moved from a forecast to a current condition.
Geopolitical Analysis
- Saudi infrastructure and Hormuz: Oil's midweek spike followed attacks and disruption around Saudi infrastructure while the Strait of Hormuz remained constrained. Friday's retreat reflected diplomacy and prospective pipeline restoration, not a resolution of the underlying conflict. The market reduced the immediate disruption premium while retaining a large structural one.
- China's role: Beijing's request that Iran help curb Houthi attacks on Saudi oil facilities was economically significant because China is both a major energy buyer and one of the few actors with leverage across the relevant relationships. The oil response suggested markets treated the intervention as more than signalling, although its durability remains untested.
- Sanctions architecture: New US legislation expanded presidential authority to impose tariffs on countries purchasing Russian energy or assisting sanctions evasion. The immediate market reaction was limited, but the potential transmission channel runs through energy trade, shipping and secondary tariffs rather than through Russia alone.
What's Pertinent This Week (Week 38)?
A 5% Treasury yield did not break the Nasdaq, but it did widen the market. For capital allocation, the distinction is important. Higher discount rates are not being applied evenly. Businesses with visible growth and strong balance sheets are still attracting capital, while rate-sensitive and domestically exposed companies are paying a larger price.
The direction of policy shifted towards tighter money. The Fed and BOJ raised rates while three members of the Bank of England wanted to do the same. Energy-linked inflation is forcing central banks to contemplate restraint at the same time as parts of the economy are becoming more sensitive to financing costs. Capital can no longer assume that policy relief arrives automatically when growth slows a little.
Oil's weekly close understates the risk. Brent ended only modestly above the prior Friday, yet traded close to $110 during the week. For allocation decisions, path and volatility matter as much as the endpoint. A flat weekly number can still impose a meaningful working-capital, hedging and inflation cost.
What Will Week 39 Bring?
Tuesday, 22 September: Fed communication after the hike
Vice Chair Philip Jefferson is scheduled to speak at the Treasury Market Conference on discount-window modernisation and Treasury market functioning. With the 10-year yield around 5% immediately after a rate increase, discussion of liquidity and market functioning carries more relevance than a routine post-meeting speech normally would.
Thursday, 24 September: Planned Trump-Xi meeting in Washington
Reuters reports that President Xi Jinping is scheduled to meet President Donald Trump in Washington on 24 September, although Chinese officials had not formally confirmed the meeting as of 17 September. Tariffs, rare earths, technology restrictions and AI all sit close to the economic agenda. With technology carrying much of the resilience in US equities, any substantive change in strategic-trade constraints could challenge current pricing.
Other catalysts:
The UN General Assembly provides a venue for Middle East diplomacy while oil remains above $100. Saudi pipeline repairs, Hormuz traffic, US PMI releases and US international-transactions data all have the capacity to move inflation expectations, yields or the dollar. Their interaction matters more than a long calendar of individual releases.
Strategic positioning:
The week's lesson favours optionality over certainty. A 5% Treasury yield raises the hurdle rate, but it has not closed the equity market. Oil above $100 raises inflation risk, but the risk premium can reverse quickly on physical supply news. Balance-sheet strength, liquidity and the ability to tolerate a wider range of discount rates remain more valuable than a precise forecast of the next policy move.
Ed's Closing Bell
Back to the coffee and the Strait, and at first glance not very much has changed. The water is still calm and the S&P 500, rather neatly, finished almost exactly where it began. Both views conceal rather more movement beneath the surface.
Two central banks raised rates, another came close, Treasury yields returned to 5%, Brent approached $110 and capital continued to leave US equity funds. Markets absorbed the news, but they did so selectively.
Perhaps that is the useful point to carry into next week. Stability at a higher cost of capital is still stability, but it is a more demanding version of it. The calm surface deserves attention, just not complacency.
Final Words
There are weeks when the market moves first and the explanation follows. This was closer to the reverse: policy, oil and geopolitics all moved, while the main US index barely did. That can be useful. It shows where conviction is strong enough to survive a less forgiving backdrop.
Please conduct your own research and seek appropriate professional advice before making investment decisions.
From Gibraltar
When the cost of money reaches 5% and markets barely blink, the important question is not whether they moved, but what they chose to ignore.
Further Reading
- Federal Reserve issues FOMC statement, 16 September 2026
- Bank Rate maintained at 3.75%, September 2026 Monetary Policy Summary
- BOJ raises interest rates to 31-year high in widely expected move
- Europe's STOXX 600 falls as autos, telecoms lead broad sell-off
- Gold rises to one-week high, heads for weekly gain on easing oil prices
- Oil slides after China asks Iran to limit Houthi attacks on Saudi oil facilities
- Global equity fund outflows hit nine-week high on inflation, rate concerns
- High stakes, low bars: Trump and Xi prepare for Washington talks
- Federal Reserve September 2026 calendar
Full Disclaimer
The views expressed in this blog are my own personal market observations and reflections. They do not constitute investment advice, a financial promotion, or a recommendation to buy or sell any security. This publication is not made in my capacity as a director of Quay Financials (Gibraltar) Limited, which is authorised and regulated by the Gibraltar Financial Services Commission. You should always conduct your own research and seek independent advice appropriate to your circumstances before making any investment decision.
Information has been obtained from sources believed to be reliable, but no representation or warranty is given as to its accuracy, completeness or timeliness. Market levels and weekly changes are compiled from public market data available at 19 September 2026 and may vary by venue, instrument and closing convention. The value of investments and the income derived from them may fall as well as rise, and investors may not recover the amount originally invested. Past performance is not a reliable indicator of future results. Readers should conduct their own research and obtain independent professional advice appropriate to their circumstances before making an investment decision.