Archive edition: Week 18, 2025. The commentary and figures reflect the original publication period, not current market conditions. These are Ed le Feuvre's personal observations, not investment advice. Read the full disclaimer.
Dear Quay Financials,
Welcome back to your weekly market digest, where we turn economic drama into something you can read before your tea goes tepid. If last week tariffs and trade war was centre stage at the theatre, this week brought a new few new characters to the fore: a surprise US GDP stumble, a PCE inflation plot twist, and China doing its best impression of a poker player with a very large stack.
Quick Recap: Tariffs, Tensions, and “Wait and See”
If you remember last week’s “Great Tariff Tango” and Powell’s central bank theatrics, you’ll know we left off with markets in classic “wait and see” mode. World Market Insights - Week 17, 2025: Where Volatility Meets Perspective (and a Little Humour Never Hurts)
Week 17 ended with markets wondering with no clear direction upwards or downwards. With week 18 to be a choppy start, with mixed outcomes for week 18.
Well, the curtain rose on Week 18 with a new act: the US economy tripped over its own shoelaces, inflation made a cameo, and the US–China trade drama continued its run-albeit with a few new plot twists.
Week 18, 2025: GDP Stumbles, or.. sputters?
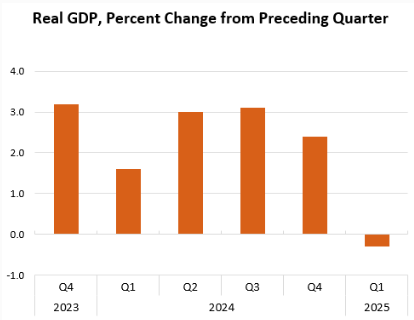 Just as markets were hoping for a smoother ride, the US GDP numbers for Q1 2025 landed with a thud: a 0.3% contraction, surprising many who expected continued growth.
The main culprit? Imports surged (which, in GDP math, is a negative see the references section below), and government spending took a breather.
Not a surprise considering the uncertainty of tariffs driving stockpiling and the government DOGE reducing government expenditure.
So, is there a recession coming? Not necessarily so….
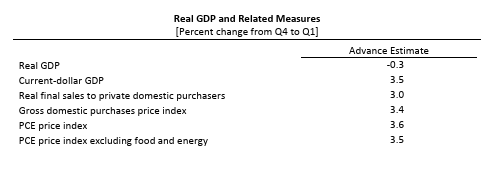
Figure 2https://www.bea.gov/sites/default/files/2025-04/gdp1q25-adv.pdf
Underneath the headline, though, private domestic demand remained strong, with real final sales to private domestic purchasers up 3.0%. So, while the top-line number looked grim on the international side, the domestic economic engine isn’t sputtering just yet….
Markets will be watching however with ‘earnings season’ commencing over the next few weeks, we can expect significant volatility.
In summary:
- Immediate reaction: Stock prices dropped on the GDP news as markets digested the surprise contraction and its implications.
- Subsequent rebound: Markets recovered as investors recognized the contraction was driven by a temporary import surge, not a collapse in core economic activity, and anticipated potential policy responses or a reversal of the one-off effects
- Ongoing caution: Despite the rebound, analysts warned of continued volatility and the risk of further slowdown if tariffs persist, and consumer/business confidence weakens.
And this week (week 18) PCE is rising
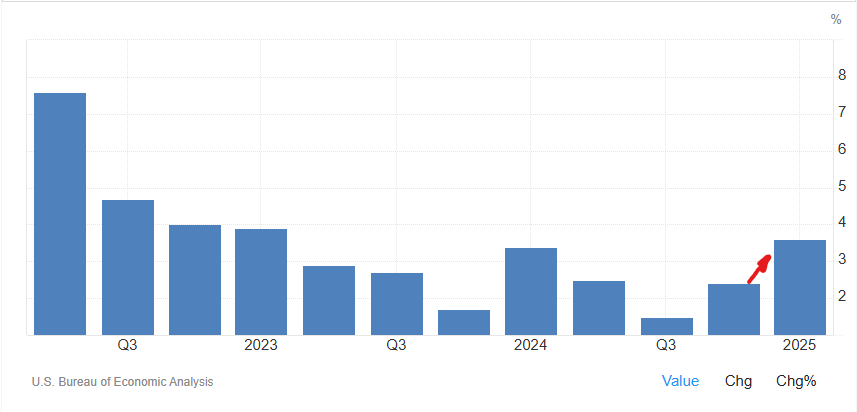 But the real scene-stealer this week was the PCE Price Index-the Federal Reserve’s preferred measure of inflation. The quarterly PCE jumped to 3.6%, up from 2.4% last quarter, and the “core” PCE (excluding food and energy) clocked in at 3.5%.
The Personal Consumption Expenditures (PCE) Price Index is the inflation gauge the Fed relies on most when setting interest rates and making monetary policy decisions. And 3.6% might be a little too spicy for the Fed’s taste.
Interestingly, the latest monthly PCE data for March showed a bit of cooling, with prices up 2.3% year-on-year-the lowest in five months, but still above the Fed’s 2% comfort zone. The result?
So what will the FED do, will they reduce interest rates and facilitate money flow into risk assets? Well the 3.6% has sparked renewed debate about when-or if-rate cuts might come…
Interest rates won’t be dropping at the next FED meeting, but all analysts and markets will be hanging off Powells words to see if they can glean what he intends to do.
In summary: The inflation battle isn’t over, and the Fed’s next move is still …. anyone’s guess… maybe even Powell’s… lets see what he says and not does.
US–China: Still Circling, Not Quite Dancing
On the trade front, the US and China are still circling each other. The US reached out about starting tariff talks, and China’s Ministry of Commerce said the “door is open”-but only if the US is serious about negotiations. Meanwhile, US officials claim China is feeling the pinch and wants a deal, but both sides are still playing hard to get. Markets are cautiously optimistic, but as one strategist quipped, “uncertainty isn’t about a singular event but rather its length.” Translation: keep your crash helmet handy.
Markets: Mixed Signals, Eyes on the Data
Despite the GDP stumble, equity markets held up, with the S&P 500 and Dow ending higher. Gold rebounded as investors hedged their bets. Corporate earnings have been mostly positive, but sticky inflation, softening growth, and ongoing trade uncertainty mean investors are still watching the data like hawks.
Looking ahead:
- US Jobs Data: Non-Farm Payrolls and unemployment figures are due, with forecasts pointing to a slowdown in hiring.
- Central Banks: The Fed, Bank of Japan, and others will be watched for any hint of policy shifts.
- Earnings Season: Big names like Apple, Microsoft, Amazon, and Meta are reporting-expect fireworks, or at least a few sparklers.
Ed’s Final Word
This week’s story? The US economy is wobbling but not collapsing, inflation is still lurking, and the trade war is more soap opera than Shakespeare. The market mood: cautious optimism, but with a healthy respect for plot twists.
As always, these are the thoughts and opinions of Ed le Feuvre and no one else’s-not even Quay Financials (Gibraltar) Limited. Please do your own research before making investment decisions.
Week 18, 2025: When in doubt, keep your seatbelt fastened and your sense of humour handy.
Further Reading:
- US GDP, Q1 2025 – BEA
- China says it is ‘evaluating’ Trump administration’s outreach on tariffs – Al Jazeera
- US PCE Price Index Annual Change – Trading Economics
- How Do Imports Affect GDP? – St. Louis Fed
- Personal Consumption Expenditures (PCE) – Investopedia
Questions, comments, or a good joke to share? Just reply to this email or contact Quay Financials directly.
Full Disclaimer
The views expressed in this blog are my own personal market observations and reflections. They do not constitute investment advice, a financial promotion, or a recommendation to buy or sell any security. This publication is not made in my capacity as a director of Quay Financials (Gibraltar) Limited, which is authorised and regulated by the Gibraltar Financial Services Commission. You should always conduct your own research and seek independent advice appropriate to your circumstances before making any investment decision.
Information has been obtained from sources believed to be reliable, but no representation or warranty is given as to its accuracy, completeness or timeliness. Market levels, weekly changes and year-to-date figures in the table are reproduced from the original Week 18 source material and have not been independently re-calculated for this web conversion. The value of investments and the income derived from them may fall as well as rise, and investors may not recover the amount originally invested. Past performance is not a reliable indicator of future results. Readers should conduct their own research and obtain independent professional advice appropriate to their circumstances before making an investment decision.
