Archive edition: Week 20, 2025. The commentary and figures reflect the original publication period, not current market conditions. These are Ed le Feuvre's personal observations, not investment advice. Read the full disclaimer.
Dear Quay Financials,
Welcome to your Week 20 market update. After last week’s “flat and cautious” mood, this week delivered a sharp reversal, with risk assets staging a powerful rally as trade tensions eased and inflation data surprised to the downside, is the spring starting to unfurl? As always, I’ll reflect on what’s changed, what hasn’t, and what it means for private equity and risk assets. Grab your coffee (and maybe a croissant this time) as we dive in for the Sunday morning.
Recap: What Changed This Week?
Last week, I wrote about the markets treading water, central banks holding the wheel, and investors waiting for a sign.
World Market Insights – Week 19, 2025: Markets Pause, Macro Questions Linger
This week, we got several signs that the coil is unwinding:
- US–China Tariff Truce: The Trump administration and China reached a temporary truce, slashing tariffs on both sides for 90 days. The US cut tariffs on Chinese imports to 30%; China reciprocated with a 10% tariff on US goods. This breakthrough, along with new trade deals with the UK and Middle Eastern partners, helped erase much of the “tariff premium” weighing on equities.
- Inflation Surprise: US consumer inflation (core CPI) for April rose just 0.2%, below expectations. This cooled fears of persistent inflation and revived hopes for a possible Fed rate cut later in the year. Next month prediction remains at 91% likely no rate cuts in the US but UK
- Interest Rate Movement: In the UK, the Bank of England cut its base rate by 0.25% to 4.25% (the third cut in six months) as inflation continued to moderate and economic growth slowed. This move was widely anticipated and added to the global sense that monetary policy may be loosening at the margin. CME forecasts for the US still sees the first US rate cuts in the late summer.
- Tech and Small Caps Lead: Tech giants like Nvidia, Tesla, Meta, Amazon, and Alphabet surged, with the Nasdaq up a whopping 7% for the week. Even small caps and the Russell 2000 joined the party, signalling broader risk appetite.
- Markets rotate out of Gold: After a stellar run, gold dropped 4% (its largest weekly fall of the year) as investors rotated out of safe havens and back into equities. A good sign.
Weekly Market Table
| Index/Asset | Weekly Change | YTD Status / Comment (2025) |
|---|---|---|
| S&P 500 | +5.3% | +1.3% |
| Nasdaq | +7.2% | -0.5% |
| Dow Jones | +3.4% | +0.3% |
| DAX (Germany) | Record high | +30% from April low |
| FTSE 100 | +1.5% | Near highs |
| Gold | -4% | Significant rotation out into risk assets |
| Bitcoin | Near record highs | Again!!..... |
The Flow: From Fear to FOMO
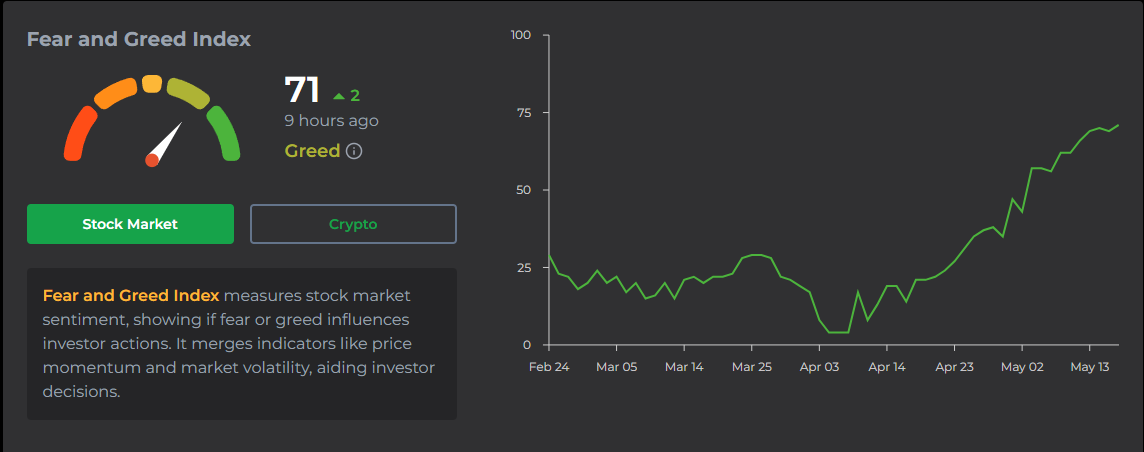
It’s remarkable how quickly sentiment can shift. Just a few weeks ago, markets were fretting over sticky inflation, weak GDP prints, and the risk that “higher for longer” rates would choke off growth. This week, a combination of diplomatic progress and softer inflation data triggered a classic “risk-on” rotation, and the FOMO (“Fear Of Missig Out”) seems to have commenced. The S&P 500 and Nasdaq not only erased their year-to-date losses, but tech stocks posted some of their biggest weekly gains in years.
Even the Dow, which had lagged in recent months, broke higher and reclaimed its uptrend. Germany’s DAX hit a record high, up an astonishing 30% from its April low-a reminder that global risk appetite is alive and well.
What’s Driving the Turnaround?
- Tariff Relief: The US–China truce and new trade deals have removed a major overhang, at least for now. With tariffs slashed, companies can plan and invest with more confidence, and supply chains get a much-needed reprieve.
- Inflation Cooling: The softer CPI print has investors betting that the Fed may not need to keep rates “higher for longer.” This is a key tailwind for both equities and private assets, as lower rate expectations boost valuations and liquidity.
- Broader Participation: The rally isn’t just about the Magnificent Seven anymore. Small caps, cyclicals, and even some lagging sectors are catching a bid, suggesting a healthier, more sustainable advance.
Risks and Cautions
Before we get too carried away, a few words of caution (it wouldn’t be an Ed note without them):
- Trade Fragility: The tariff truce is temporary-just 90 days. Negotiations could easily unravel, and the EU is still threatening retaliatory tariffs on US goods.
- Economic Reality: The Q1 GDP contraction was still real, driven by a surge in imports and a trade deficit. Underlying vulnerabilities remain, even if sentiment has improved.
- Overbought Conditions: After such a rapid surge, markets may be due for a pause or pullback, especially as technical resistance levels are tested.
Ed’s Final Word
This week’s action is a classic reminder that markets are forward-looking and can turn on a dime when the narrative shifts. Central banks remain in the driver’s seat, but geopolitics and inflation data are the traffic lights. For private equity and risk asset investors, the message is to stay nimble, watch the liquidity cycle, and don’t chase the market higher in a fit of FOMO-patience and discipline still win the long game.
As always, these are the thoughts and opinions of mine and no one else’s-not even Quay Financials (Gibraltar) Limited. Please do your own research before making investment decisions and reach out to Quay Financials if you have any queries or follow-ups.
Further Reading:
- CNBC – S&P 500 closes higher for a fourth day, Dow jumps more than 250 points
- Babypips – Global Market Weekly Recap: May 12–16, 2025
- FXLeaders – Stock Markets Relief Rally: Dow Jones (DJIA) Breaks Higher, S&P Eyes the Highs
- Advisor Perspectives – World Markets Watchlist: May 12, 2025
- Alpha Bank – Global Markets Minesweeper (PDF)
Week 20, 2025: In markets, the only constant is change-so keep your wits, your watchlist, and your breakfast close at hand.
Full Disclaimer
The views expressed in this blog are my own personal market observations and reflections. They do not constitute investment advice, a financial promotion, or a recommendation to buy or sell any security. This publication is not made in my capacity as a director of Quay Financials (Gibraltar) Limited, which is authorised and regulated by the Gibraltar Financial Services Commission. You should always conduct your own research and seek independent advice appropriate to your circumstances before making any investment decision.
Information has been obtained from sources believed to be reliable, but no representation or warranty is given as to its accuracy, completeness or timeliness. Market levels, weekly changes and year-to-date figures in the table are reproduced from the original Week 20 source material and have not been independently re-calculated for this web conversion. The value of investments and the income derived from them may fall as well as rise, and investors may not recover the amount originally invested. Past performance is not a reliable indicator of future results. Readers should conduct their own research and obtain independent professional advice appropriate to their circumstances before making an investment decision.
