Archive edition: Week 29, 2025. The commentary and figures reflect the original publication period, not current market conditions. These are Ed le Feuvre's personal observations, not investment advice. Read the full disclaimer.
Dear Quay Financials,
As another sun-drenched July week unfolds, the markets drift by with the languid ease of a linen-clad brunch on a terrace overlooking the Cretan sea … unhurried, measured, quietly contemplative. From today for the next two weeks, that sunlit perch will be my vantage point.
Markets this week felt like the slow swirl of an ouzo glass … serene on the surface, yet quietly stirred by deeper currents … political manoeuvring, regulatory chess moves, and private capital’s restlessness … global markets’ “holiday mode” simmer with an undercurrent of tension beneath the calm.
Let’s linger over the kaimaki, set down the briki, and savour the seven days just passed; no ice required.
Recap: Where We Left Off (Week 28)
Markets enjoyed gentle gains despite tariff drama, mega tax legislation, and ongoing anticipation around digital liquidity. The "GENIUS Act" and global stablecoin legislation took centre stage, while Private Equity balanced record dry powder against a scarcity of compelling deals.
if you missed last week you can find it here: Digital Gold and the $1.2 Trillion Question
This Week: The Summer Lull, Political Undercurrents, and a Waiting Game
US & Global Equities
- S&P 500 and Nasdaq: US indices notched further all-time highs amidst drift and light volume. The AI trade endures, carrying the tech complex, while defensive sectors lagged. S&P 500 +0.3% for the week; Nasdaq +0.4%.
- Europe: Continental indices traded flat to slightly lower. FTSE 100 (-0.2%) and DAX (-0.3%) underperformed as the euro strengthened and softer economic prints revived growth concerns.
- Emerging Markets: Outflows on renewed global trade anxieties. Taiwan held firm; India and Brazil both fell over 1% on weaker risk appetite.
Gold and Digital Assets
- Gold: Clung to recent highs, off just 0.1%. Policymakers' dovish signals and tariff noise supported continued defensive positioning.
- Crypto: Bitcoin and Ethereum cooled after a torrent of ETF inflows and regulatory wins. Bitcoin down 2.5% (the first meaningful pullback since May) but aggregate stablecoin market cap reached a new high above $262B.
Macro & Policy
- Fed & Rates: The September rate cut narrative remains a key focus, with the CME FedWatch tool showing the likelihood for a cut declining from 71% last week to 61% now. Odds for "no change" have risen, reflecting more mixed economic signals and dampening the conviction of imminent easing.
- US Politics & Trade: No breakthrough in tariff negotiations; global supply chain risk remains front of mind. The "Big Beautiful Bill" remains popular with working Americans, though budget hawks grow uneasy over its impact.
- GENIUS Act & Digital Policy: Congressional hearings advanced but no floor vote yet. Core provisions; like 1:1 stablecoin reserve and monthly audits; remain likely to survive. MiCA implementation in Europe moves forward.
Weekly Market Table
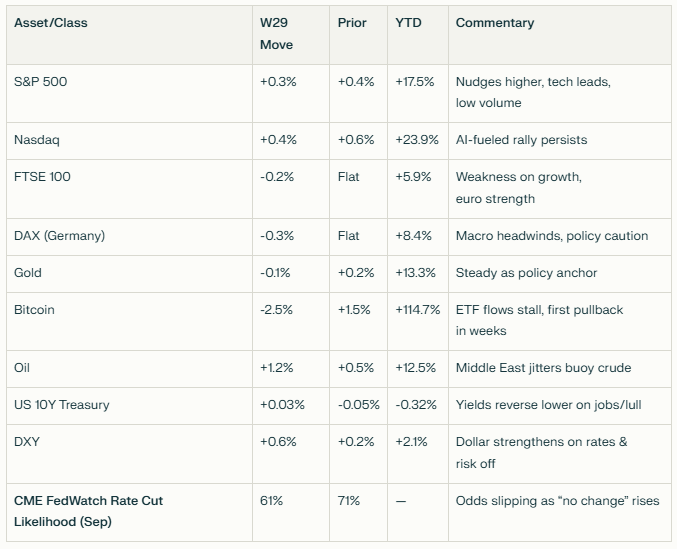
W29 Move: This week’s move. Prior: Previous week’s move. YTD: Year-to-date performance. CME FedWatch reflects market-implied probability for a rate cut at the Fed’s September meeting.
What’s Pertinent This Week?
- Political & Fiscal Undercurrents: Focus sharpened on the fiscal implications of the "Big Beautiful Bill." Growing budget deficit and rising inflation concerns featured in policy conversations, while trade gridlock persisted. Does this Bill smell of financial repression? Lets look at this a little below.
- Stablecoins & Digital Infrastructure’s March: Even with “risk off” in crypto prices, capital flowed into regulated stablecoins and infrastructure rails (custody, compliance, treasury management) attracting new venture and PE capital. MiCA’s final consultation opened in Brussels.
- Private Credit Gets Summer Hot: With traditional PE deal flow lagging, GPs and LPs rotated to private credit for yield and stable deployment as public credit spreads stabilize.
- IPO Hopefuls Pause: Several high-profile tech IPOs delayed until Q4 or 2026 as boards await clearer signals on rates and market sentiment.
- Safe Havens Hold Steady: Gold, US dollars, and short-duration Treasuries provided portfolio ballast. Low volatility signalled markets content to wait and watch.
Private Equity’s Macro Insights
Dry Powder: Patience or Peril?
Private equity globally now sits atop more than $1.3 trillion in uninvested buyout dry powder, with nearly a quarter sitting idle for over four years. Robust fundraising provides flexibility and firepower, but the environment is parched: deal volumes are muted, sellers cling to 2021 valuations, and exit windows remain scarce. The delicate balance for GPs: deploy capital prudently or risk pressure from LPs but avoid chasing deals or overpaying.
Private Credit as a Valve:
Direct lending, bespoke credit, and hybrid capital solutions have become preferred deployment routes as sponsors eschew steamy equity market prices, helping maintain returns and activity.
Digital Asset Infrastructure: Quiet Consolidation
Investment remains concentrated in digital financial rails (custody, compliance, and corporate onboarding) amid legislative uncertainty. Sovereign and pension capital continues to favour infrastructure providers, while M&A interest climbs among compliance and custodial platforms.
Interest Rates: Changing Expectations
A subtle but significant shift this week: the likelihood of a September Fed rate cut, as tracked by CME FedWatch, fell from 71% to 61%, with odds for “no change” rising as economic data delivers a less conclusive case for immediate easing.
The Economic Data Behind the Shift:
Several key data points contributed to this recalibration:
- Stronger retail sales rebounded 0.6% in June after two consecutive monthly declines, beating expectations of just 0.1%.
- Resilient employment showed 147,000 jobs added in June, with unemployment falling from 4.2% to 4.1%.
- Rising inflation pressures saw CPI accelerate to 2.7% annually in June from 2.4% in May ….. the highest since February.
Fed Officials' Divided Views:
The mixed signals created a clear split among policymakers. Fed Governors Christopher Waller and Michelle Bowman argued for cuts as early as July, with Waller stating the Fed should "not wait until the labour market deteriorates". However, Chair Jerome Powell and others preferred caution, citing tariff-related inflation risks and noting that "most professional forecasters expect a meaningful increase in inflation over the course of this year".
Private Equity impact
This data-driven shift reflects markets pricing in the Fed's increased caution about cutting rates while inflation pressures persist and the economy shows mixed but not clearly deteriorating signals. The shift keeps PE sponsors in "ready, not rushing" mode as the cost of capital outlook remains fluid.
Financial Repression – The New Old Risk
The FT’s “new era” warning argues governments will lean on below-inflation rates, captive bond buyers and gentle capital gates to deflate debts. Savers lose, real-asset owners win. For PE, that’s a tailwind: operational alpha, inflation-linked cash flows and global dispersion outmuscle repressed public yields.
While budget maths on Trump’s bill and his tariff ‘tweets’ over the last few weeks have revived discussions of a stealth financial repression, my attention this week is still monetary with the Fed.
Next week, I'll will look see what these fiscal rumours of Napier’s favourite … “financial repression” from a Greek island… a fitting place, given its history with austerity and debt default.
Ed’s Final Word
Week 29 was a lesson in strategic patience. Private Equity’s mantra remains: keep calm, deploy wisely, and be prepared to act ambitiously when market signals align.
As always, these are my thoughts and not advice. For further discussion, reach out to Quay Financials.
Further Reading
- CME FedWatch Tool
- FT – Get ready to embark on a new era of financial repression
- Bain & Company – Global Private Equity Report 2025
- McKinsey – Private Markets Review Midyear 2025
- Preqin – Q2 2025 Private Equity Update
- World Economic Forum – Financial Repression: What is it?
- Wikipedia – Financial Repression
- PitchBook – H1 2025 Global PE Overview
- BlackRock – Private Credit Outlook 2025
- Boston Consulting Group – Fintech & Infrastructure 2025
- S&P Global – Digital Asset Infrastructure Report 2025
- Crypto Valley Journal – Weekly Review
- Atlantic Council – The Stablecoin Race
- Park Avenue Securities – Monthly Market Commentary
- Morgan Stanley – July 2025 Global Equity Outlook
- DLNews – GENIUS Act and Stablecoin Regulation
Week 29, 2025: The brunch is still being set - but before autumn, expect bold flavours to return.
Full Disclaimer
The views expressed in this blog are my own personal market observations and reflections. They do not constitute investment advice, a financial promotion, or a recommendation to buy or sell any security. This publication is not made in my capacity as a director of Quay Financials (Gibraltar) Limited, which is authorised and regulated by the Gibraltar Financial Services Commission. You should always conduct your own research and seek independent advice appropriate to your circumstances before making any investment decision.
Information has been obtained from sources believed to be reliable, but no representation or warranty is given as to its accuracy, completeness or timeliness. Market levels, weekly changes and year-to-date figures in the table are reproduced from the original Week 29 source material and have not been independently re-calculated for this web conversion. The value of investments and the income derived from them may fall as well as rise, and investors may not recover the amount originally invested. Past performance is not a reliable indicator of future results. Readers should conduct their own research and obtain independent professional advice appropriate to their circumstances before making an investment decision.
