The views expressed are Ed le Feuvre's personal market observations and do not constitute investment advice, a financial promotion or a recommendation to buy or sell any security. Read the full disclaimer.
Dear Quay Financials,
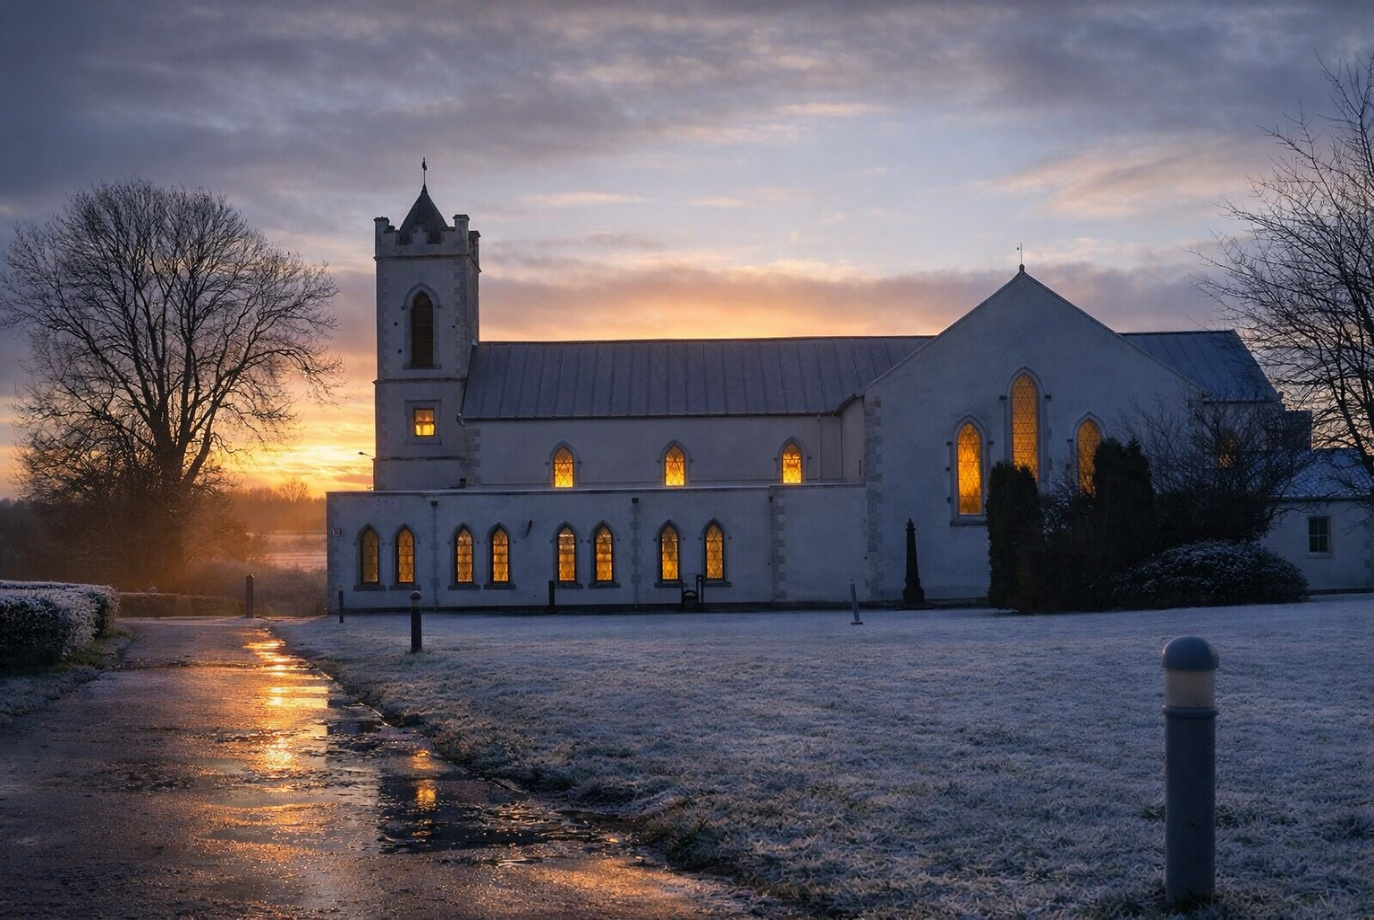
Sunday brunch in the heart of Ireland has a different rhythm. Baileborough this morning is quiet in that particular post-funeral way: the wake concluded, stories told late into last night over Irish tea, stout, and sandwiches. The morning chapel finally emptied post funeral and interment, and food laid out with quiet generosity at the Balie Hotel.
There is something profoundly steady about an Irish wake. Grief is acknowledged directly, but it is not theatrical. Life is remembered in detail. Time is allowed to pass without anyone pretending it has not shifted.
A strangely similar tone to markets this week.
After last week's air-pocket and margin-call theatre, the screens stopped shouting. Prices steadied. Conversations softened. There was a sense of composure returning. But composure is not the same thing as resolution. At a wake, the community gathers not because the loss is undone, but because it must be absorbed.
So the more awkward question lingers. When prices rebound after a shock, are we witnessing confidence rebuild, or simply pressure release? There is a difference between investors stepping back in with conviction, and investors stepping away from the cliff edge because the wind has momentarily dropped.
Week 8 felt more like the latter: measured, selective, and still dependent on the idea that policy will remain "helpful enough" if the data stays "good enough".
Relief rallies are comforting. They are also selective with the truth.
Let's turn to the week.
Recap: Where We Left Off (Week 07)
Last week's tone was fragility, not fear. The story was not recession, but how quickly "certainty" can wobble when positioning is crowded and leverage is quietly doing the heavy lifting.
What we expected was a messy digestion of hotter reality: fewer cuts, stickier yields, and risk assets forced to re-price that inconvenience. What occurred was exactly that, with a sharper edge in the more duration-sensitive corners.
What surprised was not that markets fell, but how quickly the plumbing mattered again: gold and Bitcoin both behaving less like ideological assets and more like collateral in a system briefly short of air.
What did not materialise was any true cross-asset panic. The system bent, it did not break. Week 8 was the natural sequel: a controlled exhale, not a fresh expansion.
This Week: Return of the Relief Rally; When Markets Buy Time, Not Truth
Weekly Market Table
| Asset | Week 08 2026 close | Week 07 2026 close | WoW | YTD | Comment |
|---|---|---|---|---|---|
| S&P 500 | 6,910 | 6,836 | +1.07% | -0.29% | Recovers part of the prior week's tech-led drawdown as "soft landing with fewer cuts" becomes the default setting. |
| Nasdaq Composite | 22,886 | 22,547 | +1.51% | -3.00% | Growth/AI names stabilise; leadership still narrow but buyers tiptoe back into the complex. |
| Russell 2000 | 2,664 | 2,647 | +0.65% | +5.11% | Small caps edge higher, but Friday's mild dip betrays nerves around higher-for-longer rates for levered balance sheets. |
| FTSE 100 | 10,687 | 10,446 | +2.30% | +8.27% | Grinds higher on banks and energy; a classic "value and yield" week rather than a growth story. |
| STOXX Europe 600 | 631 | 618 | +2.08% | +7.13% | Continental Europe inches to new highs, leaning on defensives and quality exporters. |
| Nikkei 225 | 56,826 | 56,942 | -0.20% | +12.07% | Japan holds onto extraordinary YTD gains; weak GDP tempers enthusiasm, but positioning remains long. |
| Hang Seng Index | 26,413 | 26,567 | -0.58% | +2.30% | China/HK tread water: bargain-hunters active, conviction still thin under the surface. |
| Gold ($/oz) | 5,112 | 5,043 | +1.37% | +12.87% | Rebuilds altitude after the early February air pocket; safe-haven status intact despite the recent flush. |
| Bitcoin (BTCUSD) | 67,984 | 68,812 | -1.20% | -21.79% | If Bitcoin cannot rally during a risk reset, then liquidity conditions may be less forgiving than equity indices suggest. |
| WTI Crude ($/bbl.) | 66.4 | 62.9 | +5.57% | +13.78% | Edges higher on modest demand optimism and supply discipline, but still feels more cyclical than geopolitical. |
| US 10Y Treasury | 4.09% | 4.05% | +0.99% | -0.97% | Long yields nudge up as markets re-price fewer cuts in 2026, but no sign yet of a genuine tantrum. |
| US 2Y Treasury | 3.48% | 3.42% | +1.75% | 0.00% | Front end inches higher; the "three cuts this year" dream slowly converges with reality. |
| JPY 30Y Treasury | 3.32% | 3.44% | -3.49% | -2.64% | Japan curve barely moves; BOJ continuity keeps JGBs an anchor rather than a signal. |
| US Dollar Index (DXY) | 97.8 | 96.88 | +0.95% | -0.09% | Dollar finds a modest bid as US data stay "good enough" and Europe/Japan disappoint at the margin. |
Week 8 delivered a gentle risk-on reset: US and global equities clawed back some of February's tech-led damage, gold quietly rebuilt its safe-haven sheen after the margin-call shock, and rates and the dollar inched higher as markets shifted from trading the last CPI print to trading the Fed's path.
US & Global Equities
- US indices clawed back ground, but the feel was distinctly "repair" rather than "breakout": a steady bid, narrow leadership, and a market still sensitive to any whisper of rates re-accelerating.
- The behavioural tell was in what did not happen. After last week's wobble, you might expect defensives to lead and credit to tighten aggressively. Instead, markets chose selective risk again, as if the prior shock was a temporary liquidity event, not a message.
- Europe ground higher in its usual late-cycle way: banks, energy, dividends, and a quiet assumption that "US resilience" remains a global import good.
- Japan held onto its extraordinary year-to-date gains, but the political overlay is becoming harder to ignore, particularly as fiscal ambition meets a market increasingly willing to price higher rates.
Gold, Digital Assets and Other Assets
- Gold's move was small, but informative. After last week's flush, it rebuilt rather than surged. That is what "insurance" looks like when it is being re-purchased quietly, not chased loudly.
- Bitcoin's failure to rally was the tell. While equities repaired, it drifted lower, reinforcing the uncomfortable truth that it remains a liquidity instrument first and a monetary alternative second. When the tide rises and the highest beta asset does not lift, conditions are not as forgiving as they appear.
- Oil edged higher, but it felt cyclical, not geopolitical: more about demand expectations and supply discipline than geopolitical premium.
Macro & Policy
- Yields and the dollar both nudged higher. The market was still willing to back the growth story, but it became less generous in how many Fed cuts it was prepared to price.
- The key behavioural contrast was that risk assets rose alongside slightly firmer yields. That is not easing-driven euphoria. It is a market buying time, hoping growth holds up even if policy becomes less obliging.
- In the background, Japan remains the global macro subplot with teeth: fiscal ambition is rising, and rate risk is no longer theoretical. That matters because it is one of the few levers left that could genuinely disturb the global "liquidity weather".
Geopolitical Analysis
- Japan is the geopolitical-macro hybrid worth watching: a new fiscal posture and an increasingly politicised rate environment is precisely the sort of cocktail that can spill into FX and global duration, even if equities pretend otherwise for now.
- The broader geopolitical tone was not "escalation" but "background noise returning". Markets behaved as if last week's shock was an internal event, not the start of a wider regime shift. That may prove correct. It may also be complacency in a calmer suit.
What's Pertinent This Week (Week 08)?
Relief is not the same as belief. Capital re-entered risk, but largely in the same indices and sectors that had just been forced lower. The S&P 500 recovered +1.07% and the Nasdaq +1.51%, yet both remain negative year-to-date. For capital allocation, that distinction matters. Repair rallies can fade as quickly as they form.
Rates rose, and equities still rose. The US 10-year nudged higher again, yet risk assets advanced alongside it. This was a market choosing to tolerate tighter financial conditions for a little longer in exchange for the growth narrative staying intact. Duration risk is being deferred, not resolved.
Gold rebuilt without drama. Up +1.37% on the week, gold did not need to surge to justify its role. The move was measured, almost restrained, but it signalled that investors were willing to keep insurance on even as they tiptoed back into equities. Guarded participation is very different from unhedged optimism.
The tell: Bitcoin did not participate in the repair. Down -1.20% on the week and still roughly -22% year-to-date, it behaved less like a recovering risk asset and more like residual stress. In a genuine relief phase, high beta assets tend to lead. This week Bitcoin did not. Liquidity conditions may therefore be less forgiving than equity indices suggest.
What Will Week 09 Bring?
Wednesday, 25 February: NVIDIA earnings
A genuine stress-test of the market's current posture. If the index repair has been leaning on the idea that "AI is still fine", then NVIDIA is the week's lie detector. The question is not whether numbers are strong, but whether expectations are too comfortable. In a relief rally, leadership must justify itself quickly.
Friday, 27 February: US PCE and the growth-inflation mix
This is where "soft landing with fewer cuts" either settles into acceptance or begins to fray. If the inflation pulse re-accelerates, yields will not remain patient for long. The rally can tolerate firm rates for a week. It cannot ignore a renewed pricing of policy restraint.
Other catalysts:
Japan's policy mix continues to simmer. Fiscal ambition alongside a rate environment that is no longer theoretical is one of the few global narratives capable of disturbing the broader liquidity backdrop. If that hinge moves, it will not stay local.
Strategic positioning:
This still feels like a market choosing optionality over commitment. The rebound has been orderly, but narrow, and duration remains the unresolved variable. The prudent stance is to recognise the move for what it is: repair. Participation is reasonable. Keep flexibility, keep liquidity, and keep exits unlocked.
Ed's Closing Bell
Baileborough is quiet now and soon I will fly back to the Rock. The wake finished, the stories told, and the gentle order of community has done its work. Week 8 had that same quality: the shock passed, prices calmed, but the engine under them did not fundamentally change.
The market habit on display was familiar: when discomfort arrives, we re-price quickly, then immediately start searching for the nearest narrative that allows us to resume. This week the narrative was "we can still have growth, and the Fed can still be kind". It might even be true. But it is also a preference disguised as a forecast.
The unresolved discomfort is duration. Not the magnitude of risk, but how long it has to be carried. Relief rallies are easy to buy. The harder question is whether the market can hold itself together through the next two or three data prints, the next earnings reality check, and the next policy moment where "cuts" are replaced by "patience".
Risk, in the end, is not the drop you survive. It is the story you keep telling yourself while you wait for the next one.
Final Words
As always, these reflections are my own. They are not the views of Quay Financials (Gibraltar) Limited, nor anyone sensible enough to keep their market opinions to a quiet coffee rather than a Sunday dispatch. Nothing here is investment advice, a financial promotion, or a recommendation to buy or sell any security.
Quay Financials (Gibraltar) Limited is authorised and regulated by the Gibraltar Financial Services Commission. Please conduct your own research and seek independent advice appropriate to your circumstances before making any investment decision.
Markets can turn faster than the Levanter can roll across Gibraltar, and anyone selling certainty about next week is usually selling something else as well. Stay curious, do your own work, and when the fog returns, keep a steady hand and a sceptical eye.
God Bless Hazelene. May her gentle soul rest in peace. Her love endures in those she raised and those she steadied. "Ar dheis Dé go raibh a hanam."
From Ireland
The rally returned, but conviction stayed selective, and the calm felt earned more by exhausted sellers than enthusiastic buyers.
Further Reading
- Week 7, 2026: When “Cooler CPI” Couldn’t Calm a Crowded Trade
Full Disclaimer
The views expressed in this blog are my own personal market observations and reflections. They do not constitute investment advice, a financial promotion, or a recommendation to buy or sell any security. This publication is not made in my capacity as a director of Quay Financials (Gibraltar) Limited, which is authorised and regulated by the Gibraltar Financial Services Commission. You should always conduct your own research and seek independent advice appropriate to your circumstances before making any investment decision.
Information has been obtained from sources believed to be reliable, but no representation or warranty is given as to its accuracy, completeness or timeliness. Market levels and weekly changes are compiled from public market data available at 12 September 2026 and may vary by venue, instrument and closing convention. The value of investments and the income derived from them may fall as well as rise, and investors may not recover the amount originally invested. Past performance is not a reliable indicator of future results. Readers should conduct their own research and obtain independent professional advice appropriate to their circumstances before making an investment decision.
