Week 43: Oil on the Boil, Bonds Below Five, and AI Passes the Hat
Dear Quay Financials,
Saturday morning in Gibraltar, hot espresso in hand, and I wonder whether markets have acquired a rather expensive sense of humour.
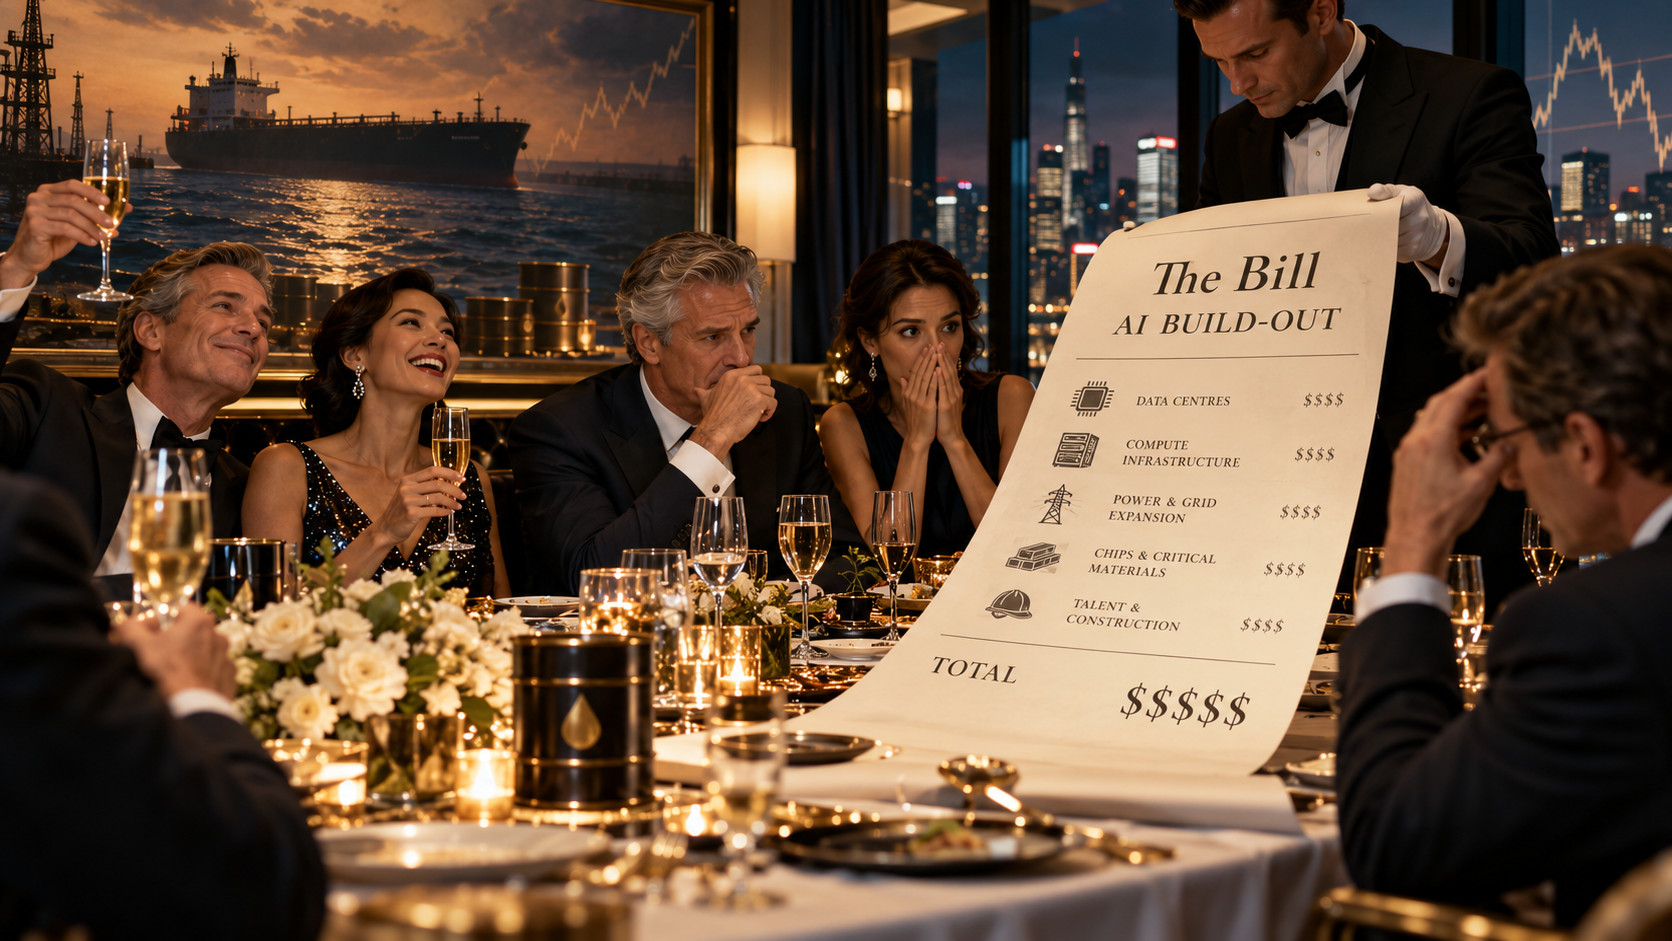
Oil is boiling above $116, Treasury yields have slipped below 5%, and the AI revolution is discovering that, after an ambitious dinner, someone still has to pick up the bill.
The Dow managed a weak smile, small caps found their feet, and Japan looked decidedly less cheerful. Higher oil prices are hardly comforting for anyone hoping inflation might quietly disappear. Meanwhile, the dip in yields has done little to stop investors asking awkward questions about AI's appetite for capital.
I've little doubt AI will change our lives. Whether every investment made in its name deserves applause is another matter.
So, another espresso, and let's see who enjoyed dinner and who's picking up the tab.
Recap: Where We Left Off (Week 42)
Last week left the Nasdaq nursing a rather uncomfortable 4.5% decline, while the Dow managed a modest smile and Europe appeared rather pleased with itself. Brent had climbed to $109.86, and Treasury yields slipped to 5.10%, despite inflation stubbornly refusing to take the hint.
The question I posed was whether investors were merely having second thoughts about AI's rather extravagant spending habits, or whether something more fundamental was beginning to unravel.
Well, Week 43 hardly settled the argument. The Nasdaq slipped another 0.7%, yet small caps found their feet, with the Russell 2000 gaining 2.0%. Europe surrendered some of its earlier enthusiasm, Japan had another miserable week, and oil continued its unwelcome ascent.
Meanwhile, bonds rallied and gold, supposedly our dependable refuge, appeared to have other plans.
Markets rarely deliver neat conclusions. This week was no exception. But the question of who pays for AI's ambitions is becoming rather difficult to ignore.
If you missed last week's dispatch: AI's Expensive Week; Oil Near $110 and Europe Looks Elsewhere.
This Week: Oil on the Boil, Bonds Below Five, and AI Passes the Hat
Weekly Market Table
| Market | Week-end level | Weekly move | Year to date |
|---|---|---|---|
| S&P 500 | 7,623.68 | -0.5% | +11.4% |
| Nasdaq Composite | 25,955.34 | -0.7% | +11.7% |
| Dow Jones | 52,215.16 | +0.4% | +8.7% |
| Russell 2000 | 2,775.90 | +2.0% | +11.8% |
| STOXX Europe 600 | 635.77 | -1.4% | +7.3% |
| FTSE 100 | 10,690.36 | -1.8% | +7.6% |
| Nikkei 225 | 62,099.29 | -4.9% | +23.4% |
| Gold New York | $4,007.90 | -4.1% | -7.7% |
| Bitcoin | $81,449 | -0.1% | -7.8% |
| Brent crude | $116.72 | +6.2% | +90.8% |
| WTI crude | $103.27 | +4.3% | +78.6% |
| US 10-year Treasury | 4.99% | -11 bps | +81 bps |
US & Global Equities
- Wall Street: The Nasdaq slipped, yet the Dow edged higher and the Russell 2000 gained 2%. Hardly the wholesale flight from risk some headlines suggested. Investors, it seems, are becoming more particular about what they are prepared to pay for.
- AI: Meta's spending plans revived an awkward question: when does extraordinary investment produce extraordinary returns? The technology may change our lives, but shareholders are entitled to ask when they might see the benefit.
- Europe: Last week's enthusiasm evaporated as higher oil prices, French fiscal nerves and mixed earnings took their toll. Kering stumbled while others held up. Apparently, even luxury handbags aren't immune to a change in mood.
- Japan: The Nikkei had another bruising week. The Bank of Japan also warned that an AI-led repricing could travel through the financial system. Wall Street's headaches, it seems, have rather good passports.
Gold, Digital Assets and Other Assets
- Gold: For something supposedly offering refuge in troubled times, gold was decidedly unhelpful. New York futures fell 4.1%, even as bonds rallied and nervousness returned. Perhaps a reminder that when investors need cash, even the safe havens can find themselves on the selling list.
- Bitcoin: Bitcoin barely moved over the week, despite plenty of excitement elsewhere. Those hoping for a wholesale rotation out of expensive technology and into digital assets were left searching for evidence. Sometimes doing very little is a statement in itself.
- Oil: Meanwhile, Brent climbed 6.2% to $116.72, with WTI gaining 4.3%. Markets are no longer worrying simply about today's barrels, but what further disruption to production and shipping might mean for tomorrow's supplies.
One suspects central bankers, already struggling to persuade inflation to behave, could have done without another helping of expensive oil.
Macro & Policy
- US Labour: Weekly jobless claims fell to 194,000, suggesting employers are still reluctant to shed workers. Encouraging, perhaps, but not quite the same as rushing to hire them. The distinction matters rather more than the headline suggests.
- Consumers & Inflation: American consumer sentiment slipped to 48.0, hardly a ringing endorsement of the economic outlook. With oil climbing again, households could be forgiven for wondering when this much-promised relief from inflation is actually going to arrive.
- The Bond Market: The US 10-year Treasury yield finally dipped below 5%. Cause for celebration? Perhaps not quite yet. Falling yields alongside rising oil prices suggest investors may be worrying as much about growth as welcoming lower inflation. As ever, the reason matters more than the headline.
- Europe: Business activity slowed, with the composite PMI falling to 51.9. The ECB faces expensive energy, French fiscal headaches and rather uninspiring growth. Holding rates at 2.50% may be the easiest decision. Explaining what comes next could prove rather more entertaining.
Geopolitical Analysis
- The Gulf: Houthi attacks in Saudi Arabia and an oil spill off the UAE coast gave crude another reason to misbehave. Saudi Arabia said the Shaybah field was still operating, which matters. There is quite a difference between fearing lost barrels and actually losing them, although the oil market rarely waits for a final invoice.
- Hormuz: The Strait remains the awkward bottleneck. Tankers, insurance and alternative routes are not particularly glamorous subjects, but they determine whether a geopolitical scare becomes a supply problem. A reassuring press release, after all, has yet to transport a barrel of oil.
- France: Across Europe, France avoided a Moody's downgrade, retaining its Aa3 rating but with a negative outlook. A reprieve, perhaps, rather than a clean bill of health. With protests, budget arguments and borrowing costs mounting, the French bond market is asking a question politicians would probably prefer to postpone: who pays?
What's Pertinent This Week?
Some weeks offer answers. This one seemed rather more interested in asking awkward questions.
Bonds: A gift, or a warning? The 10-year Treasury yield has slipped below 5%, which would usually have investors reaching for the champagne. Yet oil has climbed sharply. Are bonds celebrating inflation's retreat, or beginning to worry about growth? One would rather like to know before declaring the all-clear.
AI: The invoice arrives. I remain fascinated by what AI may achieve. What interests me increasingly is who earns the return, and when. There is a difference between building something extraordinary and buying its shares at an extraordinary price. Investors appear to be rediscovering that distinction, somewhat belatedly.
Equities: Not quite a stampede. Small caps gained while the Nasdaq slipped, Europe lost its recent sparkle and Japan had a thoroughly miserable week. That is not one tidy risk-off trade. Perhaps the herd is simply breaking into smaller groups, each with its own view of what constitutes value.
Oil: Geography has a price. Tankers, insurance and shipping routes seldom make for exciting dinner conversation, until a disruption reminds us how dependent the global economy is on them. Every extra dollar on a barrel finds its way into someone's costs. Central bankers may prefer to discuss expectations; businesses still have to pay the freight.
The common thread? Markets are becoming less willing to take an attractive story at face value. About time, some might say.
What Will Week 44 Bring?
If Week 43 was full of awkward questions, Week 44 may provide a few answers. Although, knowing markets, probably not the ones we were expecting.
Wednesday, 28 October: The Fed takes centre stage. Kevin Warsh and his colleagues must weigh expensive oil against signs of softer growth. The decision matters, but I suspect what Warsh says afterwards will matter rather more. As ever, markets will be listening for what he doesn't say.
Thursday, 29 October: A rather crowded diary. US GDP and PCE inflation arrive, alongside the ECB's latest policy decision. Strong growth, stubborn inflation or something altogether less comfortable? Central bankers may find themselves wishing the economic calendar was a little less enthusiastic.
AI faces another examination. Microsoft and Alphabet report on Wednesday, followed by Amazon on Thursday. After Meta's expensive week, investors will be asking whether the AI revolution is beginning to earn its keep or merely developing an increasingly impressive appetite for capital.
My watchpoint: Oil, bonds and technology valuations are telling slightly different stories. Next week's challenge is deciding which deserves the greater attention.
One thing is certain: there will be no shortage of opinions. Evidence may prove rather harder to come by.
Ed's Closing Bell
This week has left me with a familiar irritation: markets seem perfectly happy to tell us what happened, but rather less inclined to explain why. Oil climbed, bonds rallied and small caps found an audience while their larger technology cousins lost some of theirs. A tidy narrative? Not particularly.
I remain fascinated by AI. Yet the older I get, the less convinced I am that being right about the future automatically makes you right about the price. The history of markets is littered with brilliant ideas that made rather poor investments for those who arrived with too much enthusiasm and too little arithmetic.
Perhaps the sensible response is neither to join the chorus nor storm out of the theatre. Keep questioning, keep some room to manoeuvre, and never confuse a compelling story with a compelling valuation.
Now, where did I leave that espresso?
Final Words
As ever, these are my own observations, not investment advice or the last word on anything. If they've entertained, challenged or simply made you question the week's headlines, then I've achieved something useful.
Markets have a wonderful habit of making fools of those who claim certainty. I've been watching them long enough to know that being convinced is no substitute for being curious.
So, do your own homework, question the consensus and keep a healthy respect for what you don't know. Anyone promising to tell you precisely what happens next week is either considerably cleverer than I am, or selling something.
Have a wonderful weekend, and keep the espresso strong.
From the Rock
Stay curious, stay thoughtful, and never mistake conviction for certainty.
Further Reading
- How Major US Stock Indexes Fared on Friday, 23 October — Associated Press
- European Stocks Retreat as French Turmoil and Oil Weigh — Reuters
- Oil Prices Jump on Saudi Attacks and Supply Concerns — Reuters
- Gold Heads for a Steep Weekly Loss — Reuters
- US Weekly Jobless Claims Near 57-Year Lows — Reuters
- Eurozone Growth Slows Amid Rising Costs — Reuters
- France Spared a Moody's Ratings Downgrade — Reuters
Quay Financials disclaimer
The views expressed in this blog are my own personal market observations and reflections. They do not constitute investment advice, a financial promotion, or a recommendation to buy or sell any security. This publication is not made in my capacity as a director of Quay Financials (Gibraltar) Limited, which is authorised and regulated by the Gibraltar Financial Services Commission. You should always conduct your own research and seek independent advice appropriate to your circumstances before making any investment decision.
Information has been obtained from sources believed to be reliable, but no representation or warranty is given as to its accuracy, completeness or timeliness. Market levels and weekly changes are compiled from public market data available at 24 October 2026 and may vary by venue, instrument and closing convention. The value of investments and the income derived from them may fall as well as rise, and investors may not recover the amount originally invested. Past performance is not a reliable indicator of future results. Readers should conduct their own research and obtain independent professional advice appropriate to their circumstances before making an investment decision.